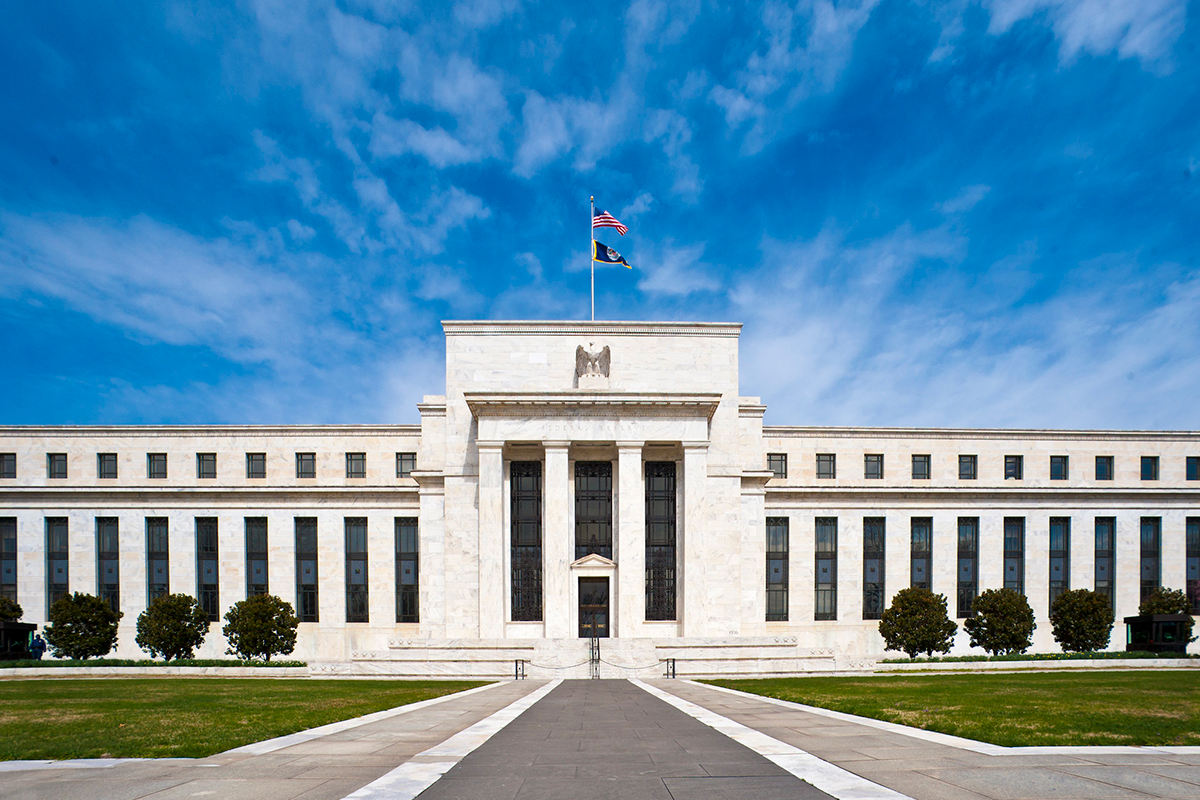
The minutes from the Federal Reserve’s September meeting were decidedly hawkish, with policymakers showing considerably more concern about inflation than about the labor market—and most officials expecting rates will need to rise again this year.
The big one: “Most participants” said another increase in the federal funds rate would likely be appropriate by year-end. Several officials also said the current policy rate was either not restrictive or only mildly restrictive, suggesting the Fed doesn’t believe it has tightened enough yet.
Why it matters: The Fed unanimously raised rates 25 basis points in September to 3.75%-4.00%. Officials said inflation remained elevated, the labor market was near full employment and economic activity continued to expand at a solid pace.
- Many believed a higher path for rates was prudent insurance against inflation remaining stubbornly high.
Inflation remains the problem: Fed officials said they had not seen sufficient progress on inflation in recent months. Energy prices and the massive AI buildout were both contributing to price pressures, while some officials warned that businesses were becoming more successful at passing higher costs on to consumers. Inflation risks were generally viewed as tilted to the upside.
AI is becoming a major economic force: The Fed repeatedly mentioned artificial intelligence throughout the minutes. AI investment is boosting business spending and supporting economic growth, but officials also worry the boom could cause demand to grow faster than the economy’s ability to supply goods and services—creating additional inflation.
- Longer term, officials believe AI could boost productivity and potential economic growth, although they acknowledged enormous uncertainty about when and by how much.
- AI may even be contributing to higher Treasury yields. The minutes noted that heavy private borrowing to finance AI infrastructure was competing for capital and contributing to higher term premiums and Treasury yields.
The consumer isn’t cracking: Consumer spending remained solid, with stock-market gains supporting spending among higher-income households. However, lower- and middle-income consumers were showing more strain as higher energy prices ate into disposable income.
And the Fed specifically mentioned mortgages: Officials said financial conditions remained supportive of the economy overall, but housing was an important exception. Mortgage rates remained elevated, residential borrowing conditions were restrictive and borrowing for home purchases remained depressed. The minutes also noted that mortgage rates had increased slightly more than the 10-year Treasury yield.
The bottom line: These minutes don’t read like a Fed preparing to declare victory. Most officials were already leaning toward another hike this year, inflation risks remain tilted higher and the AI boom is simultaneously strengthening growth and adding to inflation pressures. For mortgage rates, that’s a difficult combination: stronger growth, persistent inflation and the possibility of another Fed hike could keep upward pressure on Treasury yields and borrowing costs.