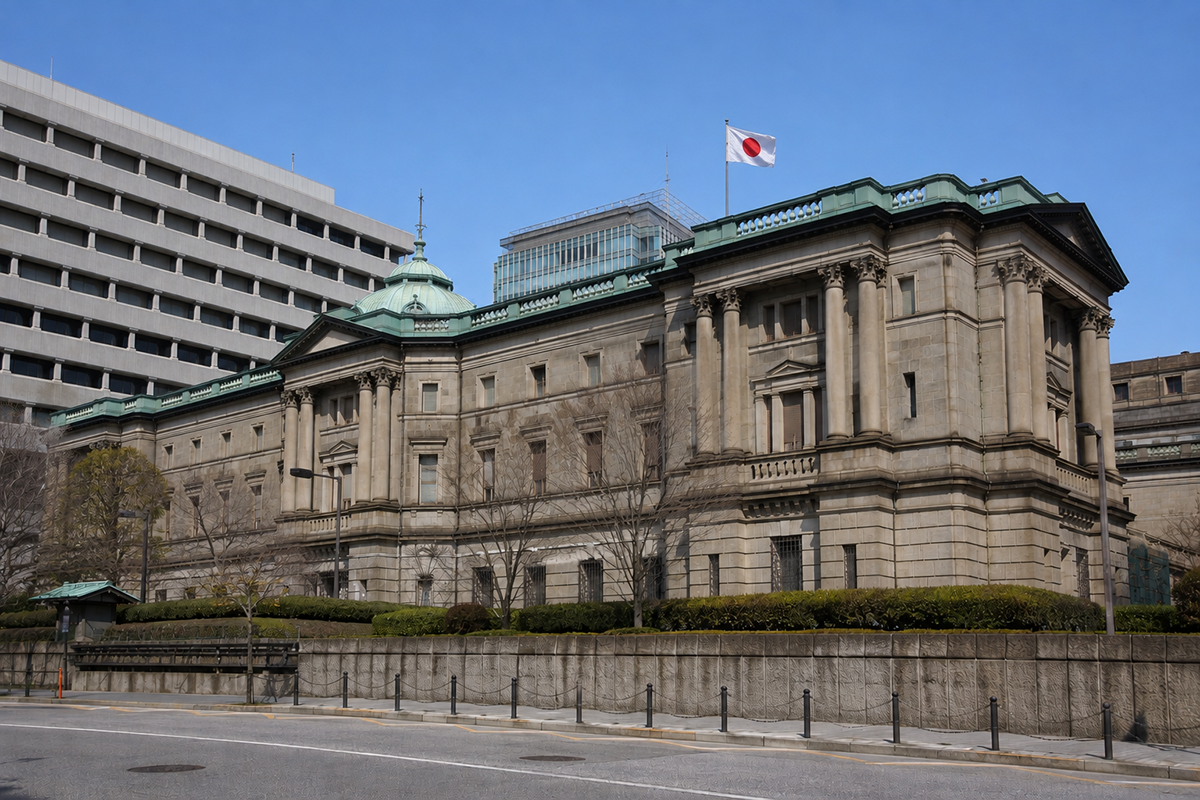
The Bank of Japan raised interest rates to their highest level since 1995 on Friday, accelerating its tightening campaign as policymakers grow increasingly concerned that persistent price pressures could push inflation above target.
Why it matters: The BOJ voted 7-2 to raise its policy rate by 25 basis points from 1.00% to 1.25%. It was the Bank’s second increase in just three months, a much faster pace than the roughly two hikes per year that characterized the earlier stages of its current tightening cycle.
- The acceleration reflects a change in the inflation picture. Government subsidies have helped hold down headline consumer inflation, but the BOJ is increasingly focused on underlying pressures.
- Higher oil prices and the weak yen are adding to concerns by increasing Japan’s import costs. The BOJ has also warned that temporary government measures are suppressing measured inflation and that higher energy and other costs could increasingly be passed through to consumers.
What They’re Saying: “Wholesale inflation remains elevated and price pressures from business-to-business trading has started to spill over into consumer prices,” the Bank said in announcing its decision.
- The BOJ also said underlying inflation has been approaching its 2% target.
Impact on US: For decades, extremely low Japanese interest rates encouraged Japanese investors to search overseas for higher returns, including in U.S. Treasuries. As Japanese rates rise, domestic bonds become relatively more attractive, potentially reducing the incentive for Japanese investors to send money abroad.
- That’s particularly important for the U.S. Treasury market because Japan remains its largest foreign holder. Treasury Department data show Japanese investors held about $1.104 trillion of Treasuries in July, which has already fallen from about $1.24 trillion in February.
- That doesn’t mean Japanese investors will suddenly abandon Treasuries. Currency hedging costs, relative yields and individual investment mandates all influence those decisions. But if higher Japanese rates gradually reduce demand for U.S. government debt, it could remove an important source of support from a Treasury market already dealing with heavy government borrowing and elevated inflation concerns.
The bottom line: Japan is moving away from the ultra-low-rate world that defined its economy for decades, and it’s doing it faster. That’s important not only for Japan’s fight against inflation but also for the U.S. bond market. Less Japanese demand for Treasuries could put additional upward pressure on long-term U.S. yields—and, by extension, mortgage rates.