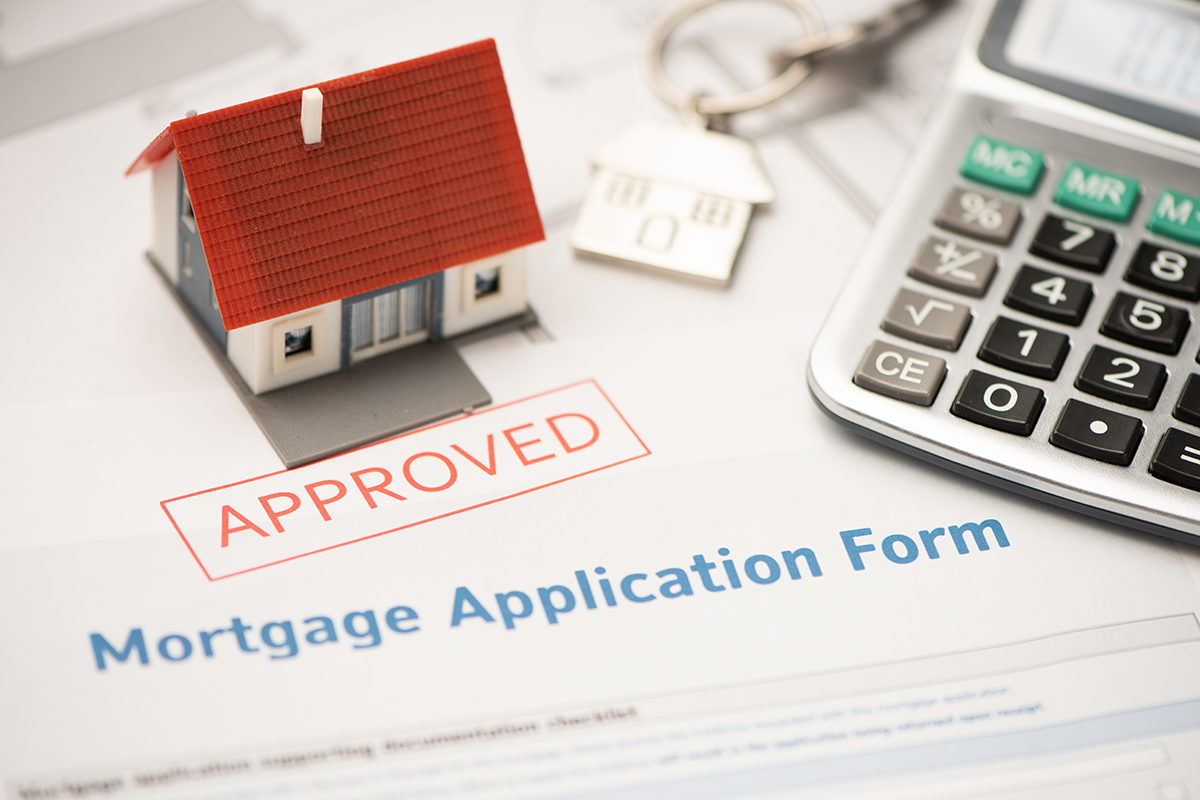
Mortgage demand fell for the fourth time in five weeks as another jump in interest rates pushed both homebuyers and homeowners looking to refinance further to the sidelines.
Why it matters: Total mortgage application volume fell 4.1% last week, according to the Mortgage Bankers Association’s weekly survey, following a 2.7% decline the previous week.
- Refinancing took the biggest hit, falling 9% from the previous week and plunging 65% from the same period last year. Purchase applications were more resilient but still declined 1% for the week and were 19% below year-ago levels.
Rising Rates: The problem continues to be rising borrowing costs. The MBA’s average 30-year fixed mortgage rate jumped 12 basis points to 6.97%, up from 6.85% the previous week. That’s the highest level since May 2025.
- The move reflects the sharp rise in Treasury yields as investors grapple with higher energy prices, persistent inflation and expectations for tighter Federal Reserve policy.
- With rates approaching 7%, fewer homeowners can benefit from refinancing while higher monthly payments continue to weigh on potential buyers.
The bottom line: The housing market is feeling the impact of the latest bond sell-off. Mortgage demand has now declined in four of the past five weeks, and with the 30-year rate approaching 7%, affordability is once again moving in the wrong direction.