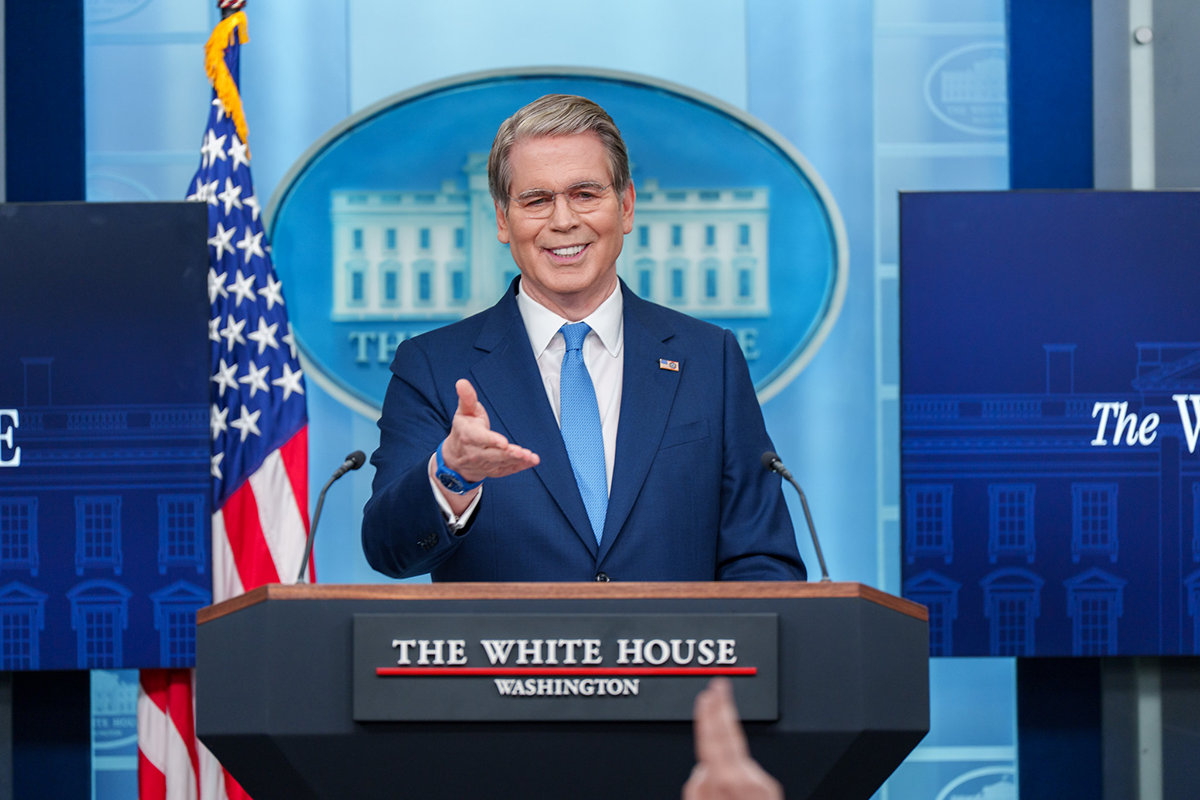
Treasury Secretary Scott Bessent says last month’s surprise expansion of the government’s bond buyback program was designed to cool what he described as a “fever” developing in the Treasury market not permanently manipulate interest rates.
Why it matters: The comments came Tuesday, just before the Treasury’s first scheduled operation under the expanded program for longer-dated securities. Treasury doubled the minimum size of those buybacks from $2 billion to $4 billion after long-term yields surged to levels not seen in nearly two decades.
- “My job is to try to push things back towards equilibrium,” Bessent said at a Breitbart News event in Washington. “I don’t believe that I can change the equilibrium price. But nothing’s ever in equilibrium.” He said the goal was to slow the momentum of a market that appeared to be feeding on itself.
Not a US Problem: Bessent also rejected the argument that the Treasury sell-off is primarily a sign that investors are losing confidence in America’s fiscal position. He argued that if investors were worried about U.S. credit, they would be selling Treasuries and moving into alternatives such as German government bonds.
- “If everyone was worried about the credit of the US, you would sell US bonds and buy German bonds — and it’s the opposite,” Bessent said. “We’re the best performing.”
- Bessent has also pushed back against comparisons between the buybacks and Federal Reserve quantitative easing, instead describing his approach as a “Treasury twist” aimed at improving conditions in parts of the bond market.
The bottom line: Bessent isn’t claiming he can permanently force Treasury yields lower. His argument is that when markets temporarily overshoot, Treasury can step in to restore some balance. The big test now is whether the expanded buybacks can actually calm long-term yields or whether the bond market’s “fever” continues.