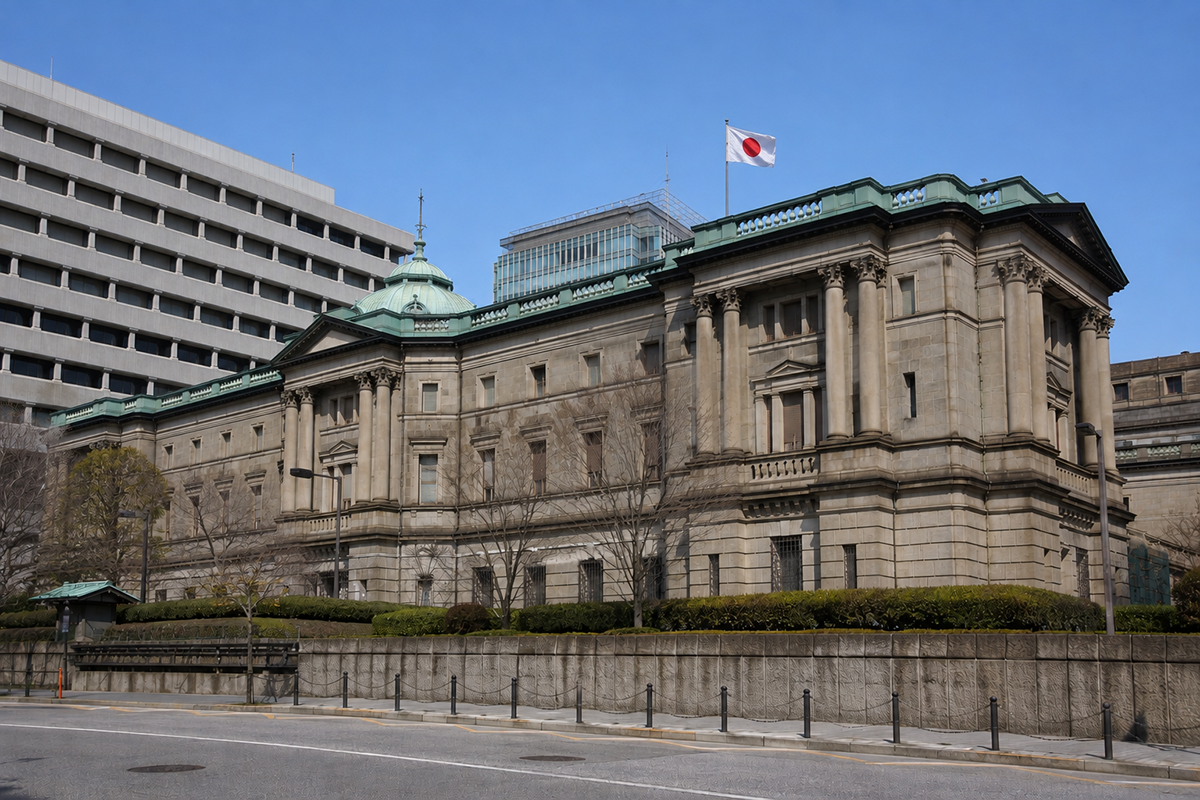
The Japanese yen is ending the week having surrendered nearly half of the gains generated by last week’s coordinated U.S.-Japan intervention, highlighting how difficult it is for policymakers to reverse the currency’s longer-term decline.
Why it matters: Japan is the largest foreign holder of U.S. Treasuries, making its battle to stabilize the yen increasingly important for American bond and mortgage markets.
- The yen initially rallied after U.S. and Japanese authorities stepped into currency markets, but much of that improvement has already disappeared despite warnings from officials in both countries that they are prepared to intervene again if necessary.
- The quick reversal underscores the limitations of currency intervention. A wide interest-rate gap between Japan and the U.S., Japan’s enormous government debt burden and continued geopolitical uncertainty remain powerful forces weighing on the yen.
What they’re saying: Robin Brooks argued on Substack Friday morning that intervention doesn’t address the fundamental problem. “This natural experiment shows that Yen depreciation is clearly about debt and yield suppression, which is something intervention can’t possibly hope to fix,” Brooks wrote. “Only debt reduction can deliver a stable currency.”
The big picture: Intervention can create sudden moves in currency markets, but unless the underlying economic forces pushing the yen lower change, Japan may find itself repeatedly defending the currency.
Impact on Mortgage Rates: The biggest risk for U.S. borrowers is what happens if currency intervention isn’t enough. If Japan becomes desperate to support the yen, Japanese investors or authorities could sell U.S. Treasuries and move money back into yen-denominated assets. Significant Treasury selling could push U.S. bond yields higher and mortgage rates along with them.